Key Definition: FTTH (Fiber To The Home)
FTTH is an optical fiber access technology that deploys the Optical Network Unit (ONU) directly at the end user's home or enterprise premises, providing dedicated fiber connectivity from the operator's central office to the subscriber. It is the highest-performance form of broadband access technology, delivering symmetrical multi-gigabit speeds over 10–20 km with latency as low as 1–3 milliseconds, and forms the physical-layer foundation for 5G backhaul, cloud computing, IoT, and the digital economy.
What Is FTTH? Definition, Architecture & Strategic Importance
FTTH represents the gold standard in broadband access—the closest fiber can reach to the end user short of Fiber To The Desktop (FTTD). In the global telecommunications hierarchy, it sits at the apex of the FTTx family: FTTH > FTTB (Building) > FTTC (Curb) > FTTN (Node). The defining characteristic of a true FTTH deployment is that optical fiber traverses the entire path from the operator's Optical Line Terminal (OLT) to an Optical Network Terminal (ONT) inside the subscriber's premises, with no copper segment in the last mile.
The FTTH network architecture comprises three core layers: the OLT at the central office managing channel control and bandwidth allocation; the Optical Distribution Network (ODN) consisting of passive optical splitters that fan out a single feeder fiber to 32–128 end users; and the ONU/ONT at the customer premises terminating the optical signal and providing Ethernet/Wi-Fi interfaces. This architecture uses a point-to-multipoint tree topology based on Passive Optical Network (PON) technology, meaning the vast majority of components between the central office and the user are entirely passive—no power, no active electronics, and therefore minimal field maintenance.
The global FTTH market was valued at approximately $120 billion in 2023 and is projected to exceed $280 billion by 2030, growing at a compound annual growth rate (CAGR) of 12.8%. China alone accounts for over 500 million FTTH users—more than 60% of the global total. This staggering scale reflects FTTH's status not merely as a telecom technology but as the fundamental infrastructure layer of the 21st-century digital economy.
>>> Need FTTH components for your deployment project? OPELINK supplies fiber optic splitters, drop cables, connectors, and complete passive optical network infrastructure. Contact sales@opelink.com for a customized quote. <<<
Global FTTH Market: Size, Regional Analysis & Growth Drivers
Three structural forces are driving FTTH deployment worldwide: consumer bandwidth demand from 4K/8K streaming, cloud gaming, and remote work; government broadband equity programs (China's "Broadband China" and "Dual Gigabit," EU's FTTH/B coverage plan targeting 308 million households by 2028, US BEAD program); and the accelerating deployment of 5G networks that require dense fiber backhaul—each 5G small cell needs its own fiber connection.
Table 1: Global FTTH Market by Region (2023–2030)
| Region |
Subscribers |
Global Share |
Penetration |
2030 Target |
Growth Driver |
Notes |
| China |
500M+ |
>60% |
85%+ |
→95% by 2030 |
¥200B+ RMB new market (2025–2030) |
Network upgrades, FTTR, East-West computing |
| Japan |
~38M |
4.8% |
~90% |
Saturated |
Upgrade-driven (10GPON) |
NTT 74.5% share; early adopter |
| South Korea |
~20M |
2.5% |
~88% |
Saturated |
Upgrade-driven |
BCN plan legacy; 10G internet rollout |
| North America |
~85M |
10.6% |
~40% |
→60% by 2028 |
BEAD program; AI data center surge |
Fibre demand +15.9% CAGR to 2025 |
| Europe (EU27+UK) |
~70M |
8.8% |
~55% |
→85% by 2028 |
EU FTTH/B 308M households target |
Germany & UK accelerating |
| India |
~35M |
4.4% |
~12% |
→35% by 2028 |
Largest growth market; >25% APAC ex-China |
Jio/Airtel fiber rollout |
| SE Asia + LATAM + MEA |
~52M |
6.5% |
10–30% |
High growth |
Greenfield opportunity |
Chinese OEMs building overseas factories |
>>> Deploying FTTH in any of these regions? OPELINK ships globally with 4-10 week lead times. Request a regional component quote tailored to your project scale. <<<
China FTTH Deep Dive: The 500 Million Subscriber Market
China's FTTH deployment is the largest infrastructure project in telecommunications history. With over 500 million subscribers and a penetration rate exceeding 85%, the market is transitioning from coverage expansion to quality upgrade. Three trends define the next phase:
Network Upgrade from GPON to 10G PON: Major operators (China Mobile, China Telecom, China Unicom) are systematically upgrading existing GPON OLTs to 10G PON (XG-PON / XGS-PON) to support gigabit broadband services. Domestic operators' fiber optic cable centralized procurement scale is estimated to reach 230 million core kilometers in 2025. The G.654.E ultra-low-loss fiber segment for computing power backbone networks alone is expected to exceed 70 billion RMB.
FTTR (Fiber-to-the-Room): A uniquely Chinese innovation where fiber extends beyond the ONT into individual rooms via invisible optical cable or transparent butterfly cable, replacing Wi-Fi mesh backhaul. This is driving a new wave of in-home fiber deployment and creating a substantial aftermarket for optical components.
Regional Rebalancing: Urban FTTH coverage is near saturation, but the "East Data, West Computing" national project is creating a new demand vector—massive fiber deployment to connect western China's data center clusters to eastern China's population centers, effectively building a national-scale optical computing fabric.
Cost Reduction Trajectory: The $300/km Milestone
One of the most consequential economic shifts in telecommunications: the cost of optical fiber has fallen from approximately $800 per kilometer in 2015 to $300 per kilometer in 2023—a 62.5% reduction in eight years. This cost curve, combined with supply chain maturation (optical cable delivery lead times compressed from 52–60 weeks in 2022 to 4–10 weeks in 2023), has fundamentally altered the economics of FTTH deployment. Projects that were marginal at $800/km are now comfortably in the green, opening vast new addressable markets in rural areas and developing economies where the business case previously failed.
>>> Sourcing fiber cable for large-scale deployment? OPELINK offers G.652.D, G.657.A2, and G.654.E fiber at competitive China-direct pricing. Get a bulk quote for your project volume. <<<
PON Technology Comparison: GPON vs EPON vs 10G PON vs 50G PON
The heart of any FTTH deployment is the PON (Passive Optical Network) technology that governs how bandwidth is shared among subscribers on a single fiber tree. Understanding the differences between PON generations is essential for network planners making technology selection and upgrade-path decisions.
Table 2: PON Technology Generations — Full Comparison
| Parameter |
GPON |
EPON |
10G PON (XG/XGS) |
50G PON |
100G PON (Future) |
| Standard Body |
ITU-T G.984 |
IEEE 802.3ah |
ITU-T G.987 / G.9807 |
ITU-T G.9804 |
ITU-T G.9804.3 |
| Year Standardized |
2003 |
2004 |
2010 / 2016 |
2021 |
In progress |
| Downstream Rate |
2.488 Gbps |
1.25 Gbps |
10 Gbps (XG-PON),10 Gbps (XGS-PON) |
50 Gbps |
100 Gbps (planned) |
| Upstream Rate |
1.244 Gbps |
1.25 Gbps |
2.5 Gbps (XG-PON),10 Gbps (XGS-PON) |
10/25/50 Gbps |
50/100 Gbps (planned) |
| Split Ratio (Max) |
1:64 (1:128 ext.) |
1:32 (1:64 ext.) |
1:128 (1:256 ext.) |
1:256 |
1:256+ |
| Max Reach |
20 km (60 km ext.) |
20 km |
20–40 km |
20 km |
20–40 km |
| Wavelength (DS/US) |
1490/1310 nm |
1490/1310 nm |
1577/1270 nm |
TBD |
TBD |
| Typical Use Case |
Legacy FTTH; still dominant globally |
Asia-Pacific legacy; some Japan/Korea |
Current upgrade target; gigabit broadband |
8K video, AI inference, enterprise |
Future-proof; post-2030 |
| Commercial Status |
Mature (declining) |
Mature (declining) |
Rapid growth phase |
Early commercial (2024+) |
Lab/demo stage |
GPON vs EPON: Which Standard Dominates?
The PON standards landscape has historically been split between two camps: GPON (ITU-T, favored by European, North American, and most Asian operators including China's big three) and EPON (IEEE, historically strong in Japan, Korea, and some cable MSO deployments). GPON's technical advantages—higher bandwidth (2.488/1.244 Gbps vs. EPON's 1.25/1.25 Gbps symmetric), larger split ratios, native TDM support for legacy services—have made it the de facto global standard for greenfield FTTH. EPON survives primarily in brownfield Asian networks and cable operator DOCSIS-provisioning-over-EPON (DPoE) architectures. For new deployments in 2025 and beyond, the question is no longer GPON vs EPON but rather whether to deploy 10G PON (XGS-PON) directly or deploy GPON now with a planned upgrade path.
>>> Selecting PON technology for your network? OPELINK provides compatible splitters, connectors, and ODN components for GPON, XGS-PON, and 50G PON deployments. Consult with our technical team. <<<
Technology Trends Shaping the Next Decade of FTTH
1. 10G PON Commercialization & 50G PON on the Horizon
The global transition from GPON to 10G PON is the single largest active infrastructure upgrade in telecom. XGS-PON (10 Gbps symmetric) is being deployed by operators worldwide to support gigabit-tier residential services and enterprise-grade symmetrical connectivity. China's operators are leading this transition at scale, with 10G PON OLT port shipments exceeding GPON for the first time in 2024. The next frontier—50G PON, standardized in ITU-T G.9804.3—entered early commercial trials in 2024–2025, targeting applications requiring sub-millisecond latency: 8K uncompressed video transport, cloud-rendered XR, and industrial machine vision over PON.
2. FTTR: Extending Fiber into Every Room
Fiber-to-the-Room (FTTR) represents the next logical extension of the FTTH architecture. Rather than relying on Wi-Fi mesh to distribute connectivity within the home, FTTR deploys a miniaturized optical network inside the premises—a central ONT with PON ports connecting to room-level optical edge ONTs via invisible fiber or transparent butterfly optical cable. China Telecom alone has deployed over 10 million FTTR households as of 2024, and the technology is driving demand for a new category of indoor optical components: bend-insensitive G.657.A2 fiber(drop cable), field-mountable SC/APC connectors, and transparent adhesive cable routing systems.
3. SDN-Controlled Intelligent Optical Networks
Software-Defined Networking (SDN) is being extended to the optical access layer, enabling operators to dynamically provision bandwidth, reroute traffic around faults, and perform zero-touch ONT activation. Combined with AI/ML-driven predictive maintenance (analyzing OTDR traces for pre-failure signatures), intelligent optical networks reduce mean-time-to-repair from hours to minutes and cut truck rolls by 30–50%.
4. Green Manufacturing & Sustainable Fiber
The fiber optic industry is undergoing a sustainability transformation. Key developments include: reduction of preform manufacturing energy consumption (the most energy-intensive step, accounting for ~70% of a fiber's embodied carbon); development of bio-based cable jacket compounds as alternatives to petroleum-derived HDPE; and the inherent environmental advantage of fiber over copper—fiber networks consume approximately 60% less energy per bit transmitted than equivalent copper-based broadband networks over their lifecycle.
FTTH Deployment Challenges & Proven Solutions
Table 3: Top 5 FTTH Deployment Challenges & Solution Matrix
| Challenge |
Root Cause |
Proven Solutions |
Real-World Impact |
| High Initial CAPEX |
Civil works (trenching) = 60–80% of project cost, prohibitive in rural areas |
Micro-trenching (2–4 cm width, 15–30 cm depth); air-blown fiber (deploy empty ducts, blow fiber on demand); government subsidy programs (US BEAD, EU CEF Digital) |
Shenyang micro-trench FTTH: 85% schedule reduction vs traditional trenching |
| Labor Shortage & High Labor Cost |
Developed markets (Japan, N. America): skilled splicer shortage; labor = 40–60% of install cost |
Pre-terminated cable assemblies (factory connectors eliminate field splicing); automated fusion splicers (12–15 sec/splice vs 45–60 sec manual); robotic blowing machines |
Pre-terminated drops: 4× faster ONT installation per household |
| Right-of-Way & Permitting Delays |
Urban: congested underground, restrictive excavation permits; months of delays common |
Air-blown micro-cable in residual duct space (2–7 mm OD fits where 13–25 mm cable cannot); sewer-deployed fiber; aerial FTTH on existing utility poles |
Tokyo: 60% faster using air-blown in congested ducts vs traditional pulling |
| Rural & Remote Deployment ROI |
Low subscriber density = decades for payback on traditional fiber builds |
Phased microduct + air-blown approach (install ducts once, blow fiber incrementally); government universal service funds; satellite/fixed-wireless hybrid for ultra-remote |
EU: 308M household FTTH/B target by 2028 includes rural subsidy mechanisms |
| Technology Standard Fragmentation |
GPON vs EPON legacy; 10G PON migration complexity; ONT interoperability issues |
ITU-T G.988 OMCI for unified ONT management; XGS-PON as convergence standard for new builds; software-defined OLTs with multi-PON line cards |
Major operators standardizing on XGS-PON for all new OLT deployments post-2024 |
>>> Facing deployment challenges? OPELINK's pre-terminated cable assemblies and air-blown fiber systems reduce installation time and labor costs. Get deployment-ready component packages. <<<
FTTH vs Alternative Broadband Technologies: A Definitive Comparison
Table 4: FTTH vs FTTB/FTTC vs HFC (Cable) vs 5G FWA vs DSL
| Dimension |
FTTH (Full Fiber) |
FTTB / FTTC |
HFC (Cable/DOCSIS) |
5G Fixed Wireless |
DSL / VDSL |
| Max Download Speed |
10 Gbps (XGS-PON),50 Gbps (50G PON) |
1–10 Gbps |
1–2 Gbps (DOCSIS 3.1),10 Gbps (DOCSIS 4.0) |
1–3 Gbps |
100 Mbps (VDSL2),1 Gbps (G.fast) |
| Max Upload Speed |
10 Gbps (symmetric) |
1–10 Gbps |
35–100 Mbps (asymmetric) |
50–500 Mbps |
40 Mbps (VDSL2),100 Mbps (G.fast) |
| Latency |
1–3 ms |
1–3 ms |
10–30 ms |
5–20 ms |
5–30 ms |
| Reliability |
Excellent (passive, immune to EMI) |
Excellent |
Good (active amps, RF noise) |
Good (weather-dependent) |
Poor (copper degradation,distance) |
| Upgrade Path |
Future-proof (same fiber, upgrade optics) |
Same as FTTH |
Requires node split + new amps |
Spectrum refarming |
End-of-life (copper retirement) |
| Lifespan |
30–50 years (fiber plant) |
30–50 years |
15–20 years (active components) |
10–15 years |
Phasing out |
| Best Use Case |
Primary broadband; all use cases |
MDU retrofit |
Cable MSO brownfield |
Rural overlay; fixed backup |
Legacy (replacing) |
| Global Trend |
↑ Rapid growth |
↑ Growth |
→ Stable (DOCSIS 4.0) |
↑ Growing as complement |
↓ Structural decline |
The comparison makes the strategic case for FTTH unambiguous: it is the only technology that combines multi-gigabit symmetrical speeds, sub-3 ms latency, passive-plant reliability with 30–50-year lifespan, and a clear upgrade path to 50G PON and beyond without replacing the physical fiber. 5G Fixed Wireless Access (FWA) is the most interesting alternative—it has seen rapid growth (T-Mobile US alone added ~4 million FWA subscribers) and serves as an effective complement to FTTH for rural and low-density areas. However, FWA's shared-spectrum architecture means per-subscriber throughput degrades with congestion in a way that dedicated-fiber PON networks do not. The industry consensus is clear: FTTH for primary broadband, FWA for the last 5–10% of addresses, and copper retirement everywhere else.
FTTH 2025–2035: Key Trends & Market Projections
1. Global FTTH Subscribers to Exceed 1.5 Billion by 2030. Driven by India's acceleration (JioFiber, Airtel Xstream), European altnet buildouts, and continued Chinese household penetration, the global FTTH subscriber base is projected to nearly double from ~800 million in 2023 to over 1.5 billion by 2030.
2. 50G PON Becomes the New 10G PON. Just as GPON to 10G PON defined the 2020–2025 upgrade cycle, 10G PON to 50G PON will define 2028–2033. The first 50G PON commercial networks will appear in China, Japan, and the Middle East by 2026–2027, targeting enterprise, mobile xHaul, and premium residential tiers.
3. FTTR Goes Global. Currently a China-centric phenomenon, FTTR is expected to cross over to premium residential markets in the Middle East, Southeast Asia, and eventually Europe by 2027–2028, driven by the same logic: Wi-Fi cannot keep pace with multi-gigabit WAN connections without fiber-grade backhaul between rooms.
4. AI-Driven Optical Network Operations. By 2030, AI/ML models trained on billions of OTDR traces will be capable of predicting fiber breaks 48–72 hours before they occur, identifying degrading splices from subtle reflectance changes, and autonomously re-routing traffic in software-defined optical networks—reducing outage minutes by an estimated 80%.
5. The $280B Market Reality. At $280 billion by 2030, FTTH represents one of the single largest infrastructure investment categories globally, comparable in scale to renewable energy and 5G RAN. For the optical component supply chain—fiber preform manufacturers, cable assemblers, connector and splitter vendors, and PON equipment makers—this represents a sustained, multi-decade demand cycle.
▶ Plan Your FTTH Deployment with OPELINK
From EPFU air-blown fiber drop cables and microduct systems to pre-terminated assemblies and GPON/10G PON connectivity solutions, OPELINK provides the complete passive optical network infrastructure for FTTH projects at any scale.
Get FTTH Solution Consultation →
FTTH Component Procurement Guide: BOM, Selection & Sourcing
This section is designed for procurement teams, project managers, and network contractors who need to source FTTH components efficiently. Whether you are planning a 1,000-home greenfield deployment or upgrading an existing GPON network to 10G PON, the following bill of materials (BOM), selection criteria, and sourcing checklist will help you make informed purchasing decisions.
Typical FTTH Project Bill of Materials (BOM)
The table below shows a standard BOM for a 1,000-subscriber GPON/XGS-PON FTTH project. Quantities and specifications should be adjusted based on your specific network design, split ratio, and geographic conditions.
| Component Category |
Specification |
Est. Qty (1K Homes) |
Key Selection Criteria |
OPELINK Product Line |
| Feeder Cable |
G.652.D, 48-96 core, underground |
5-10 km |
Attenuation <0.36 dB/km @1310nm; Tensile strength |
ADSS/Direct-buried fiber cable |
| Distribution Cable |
G.652.D, 12-24 core, duct |
15-30 km |
Compact design; jacket type (PE/LSZH) |
GYTA/GYTS fiber cable |
| Drop Cable |
G.657.A2, 1-4 core, flat/round |
1K-4K pcs |
Bend radius <15mm; connectorized or field-splice |
FTTH drop cable (indoor/outdoor) |
| PLC Splitter |
1:32 or 1:64, ABS box or LGX |
30-100 pcs |
Uniformity <1.5 dB; Insertion loss <17.5 dB (1:32) |
1x32/1x64 PLC fiber optic splitter |
| Fast Connector |
SC/APC, field-mountable |
2K-4K pcs |
Return loss >60 dB; Installation time <2 min |
SC/APC fast connector (55-type) |
| Fusion Splice Protector |
60mm, stainless steel |
1K-3K pcs |
Shrink temp; strength after splice |
Heat shrink splice sleeves |
| ODF/Fiber Patch Panel |
24-48 port, rack mount |
5-15 pcs |
Adapter type (SC/LC); density; cable management |
Optical distribution frame |
| Pigtail |
SC/APC or LC/UPC, 1m |
1K-2K pcs |
Connector type matches equipment; polish type |
SC/APC & LC/UPC pigtails |
| Patch Cord |
SC/APC-SC/APC, 1-3m |
200-500 pcs |
Type (single mode); jacket color; length |
Fiber optic patch cord |
| Air-Blown Cable (optional) |
G.652.D, micro-duct, 2-12 core |
5-20 km |
Friction coefficient; duct compatibility |
Air-blown micro fiber cable |
| Wall Box/ONT enclosure |
Plastic, waterproof, 150x100x50mm |
1K pcs |
IP rating; cable entry/exit; size |
ONT wall mount box |
Component Selection Guide: 5 Critical Decision Points
When sourcing FTTH components, procurement teams should evaluate the following five decision points to ensure compatibility, performance, and cost-effectiveness:
- Fiber Type Selection: G.652.D for feeder/distribution (standard single-mode, lowest cost); G.657.A2 for drop cable (bend-insensitive, enables tight indoor routing); G.654.E for long-haul backbone (ultra-low-loss for data center interconnect). Mixing fiber types is standard practice-choose based on the segment's bending and attenuation requirements.
- Splitter Ratio Trade-off: 1:32 for suburban (lower loss, more splitter ports needed); 1:64 for dense urban (fewer feeder fibers, higher per-port loss); 1:128 for XGS-PON high-density. Calculate your optical power budget before committing to a split ratio.
- Connector Type & Polish: SC/APC (green) is the FTTH standard for PON (minimum back-reflection); LC/UPC (blue) for equipment-side patch panels; SC/UPC (blue) for legacy GPON. Never mix APC and UPC on the same link-return loss mismatch causes performance degradation.
- Cable Jacket Material: PE (polyethylene) for outdoor underground-direct burial, UV resistant; LSZH (low smoke zero halogen) for indoor-safety compliance in residential/commercial buildings; PVC for general indoor use. Verify local fire codes before specifying jacket material.
- Pre-terminated vs. Field-Spliced: Pre-terminated drop cables (factory connectors) reduce installation time by 4x and eliminate splicing labor, but cost 20-30% more per unit. For large projects (>500 drops), pre-terminated saves total project cost despite higher unit price. For small projects or long variable-length drops, field-spliced with fast connectors is more economical.
Cost Breakdown by Component Category
Understanding the cost distribution of FTTH components helps procurement teams allocate budget and identify savings opportunities. The table below shows typical cost proportions for a standard GPON FTTH project (excluding civil works and active equipment):
| Component Category |
% of Passive Component Cost |
Cost Range (per subscriber) |
Cost Optimization Tip |
| Fiber Cable (feeder + distribution + drop) |
35-45% |
$15-30 |
Volume purchase from manufacturer; standardize fiber type |
| PLC Splitters |
10-15% |
$5-10 |
Buy in bulk; ABS box type is cheaper than LGX module |
| Connectors (fast + pigtail + patch cord) |
15-20% |
$8-15 |
Pre-terminated for large volumes; standardize on SC/APC |
| ODF/Patch Panels/Enclosures |
10-15% |
$5-10 |
High-density panels reduce rack space and cost per port |
| Splice Protectors & Accessories |
5-10% |
$3-6 |
Bulk purchase; include in cable order for bundle discount |
| Installation Tools (one-time) |
5-10% |
$3-5 amortized |
Invest in quality fusion splicer-reduces splice failures |
Quality Standards & Certifications Checklist
Before placing an order, verify that your supplier meets the following industry standards and certifications. OPELINK components comply with all relevant ITU-T, IEC, and Telcordia standards:
- ITU-T G.652.D / G.657.A2 / G.654.E: Fiber geometric and transmission characteristics
- ITU-T G.984.x / G.987.x: PON compatibility (GPON / XGS-PON component compliance)
- IEC 61754: Fiber optic connector interface standards
- Telcordia GR-326: Connector reliability requirements for single-mode connectors
- RoHS / REACH: Environmental compliance for European and global markets
- ISO 9001: Quality management system certification (manufacturer-level)
- TUV / CE / UL: Product safety certifications as applicable by region
>>> Ready to source your FTTH components? Send your BOM or project specifications to sales@opelink.com for a detailed quote with volume pricing, lead time, and compliance documentation. <<<
Why Source from OPELINK: Your FTTH Component Supply Partner
OPELINK is a specialized fiber optic component manufacturer and supplier based in Shenzhen, China-the heart of the global optical communications supply chain. With over a decade of experience serving telecom operators, ISPs, system integrators, and contractors in 80+ countries, OPELINK offers a compelling value proposition for FTTH component procurement:
Complete Product Portfolio
OPELINK provides the full range of passive optical components needed for FTTH deployment, eliminating the need to manage multiple suppliers:
- Fiber optic cables: G.652.D/G.657.A2/G.654.E, ADSS, direct-buried, air-blown, FTTH drop cables (indoor/outdoor)
- PLC splitters: 1x2 to 1x64, ABS box, LGX module, mini-block, rack-mount configurations
- Connectors & pigtails: SC/APC, SC/UPC, LC/UPC, LC/APC, FC/UPC-fast connectors, pigtails, patch cords
- ODF & patch panels: Wall-mount, rack-mount, high-density fiber distribution frames
- FTTR components: Bend-insensitive fiber, transparent butterfly cable, indoor optical distribution
- Accessories: Splice protectors, wall boxes, cable ties, fiber tools, fusion splicer consumables
Competitive Advantages
| Advantage |
Description |
Benefit to You |
| China-Direct Pricing |
Manufacturing in Shenzhen eliminates middleman markups |
20-40% cost savings vs. Western distributors |
| Global Shipping |
DHL/FedEx/UPS express; sea freight for bulk orders |
4-10 week lead times to 80+ countries |
| Quality Assurance |
ISO 9001 factory; ITU-T/IEC/Telcordia compliant products |
Field-proven reliability, low defect rate |
| Custom Solutions |
Custom cable lengths, connector types, splitter configurations |
Project-specific BOM without multiple suppliers |
| Technical Support |
English-speaking technical team; pre-sales consultation |
Reduced design risk, faster deployment |
| Volume Flexibility |
MOQ as low as 100 pcs for standard items; bulk pricing |
Suitable for both pilot projects and large deployments |
| Documentation |
Full compliance docs: test reports, RoHS, REACH, COC |
Smooth customs clearance and project audit readiness |
How to Request a Quote from OPELINK
Getting a customized quote for your FTTH project is simple and fast. Follow these steps:
- Step 1: Prepare your BOM or project specifications (component types, quantities, specifications, delivery timeline).
- Step 2: Email your requirements to sales@opelink.com or use the inquiry form on our contact page.
- Step 3: Our technical team reviews your BOM and responds within 24 hours with pricing, lead time, and compliance documentation.
- Step 4: For large projects, request a free technical consultation to optimize your component selection and reduce costs.
- Step 5: Place your order with confidence-full quality documentation and tracking provided.
>>> Start your FTTH component sourcing today. Email sales@opelink.com with your project requirements, or visit www.opelink.com/contact-us to submit an inquiry. <<<
FAQ-Frequently Asked Questions About FTTH Deployment
What is the difference between FTTH, FTTB, and FTTC?
FTTH (Fiber To The Home) brings optical fiber all the way into the subscriber's living unit, terminating at an ONT inside the premises. FTTB (Fiber To The Building) terminates fiber at the building's basement or telecommunications room, with the final 30–100 meters typically using existing copper (Ethernet or VDSL). FTTC (Fiber To The Curb) terminates fiber at a street cabinet, with the last 200–500 meters over copper. FTTH delivers the highest performance (symmetrical multi-gigabit, 1–3 ms latency) because it eliminates the copper bottleneck entirely. For greenfield deployments in 2025, FTTH is the recommended architecture; FTTB/FTTC are transitional technologies for brownfield cost-constrained scenarios.
Which is better for new deployments in 2025: GPON or 10G PON (XGS-PON)?
For all new greenfield FTTH deployments in 2025, XGS-PON (10 Gbps symmetrical) is the recommended baseline. The cost premium over GPON has narrowed to approximately 15–25% on OLT line cards and ONTs, while the capability gap is 4× downstream and 8× upstream. Deploying GPON today and upgrading to XGS-PON in 3–5 years incurs roughly 2× the total cost versus deploying XGS-PON from the start (truck rolls + ONT replacement + service disruption). The exception is ultra-low-ARPU markets where GPON's cost advantage materially impacts the business case, and an upgrade can be planned for Year 5–7 of the network lifecycle.
How much does it cost to deploy FTTH per household passed?
FTTH deployment costs vary dramatically by geography and density. In dense urban China / Southeast Asia: $150–300 per home passed. In suburban North America / Europe: $600–1,200 per home passed. In rural / low-density areas: $2,000–5,000+ per home passed. The dominant cost driver is civil works (trenching, duct laying, surface restoration), which typically accounts for 60–80% of total deployment cost. The cost of the fiber cable itself has fallen to approximately $300/km (2023) and is a relatively small fraction of the total. Technologies that reduce civil works costs—micro-trenching, air-blown fiber, aerial deployment on existing poles—have the largest impact on per-home-passed economics.
What is FTTR (Fiber-to-the-Room) and why is it important?
FTTR extends the optical fiber from the ONT at the home entry point to individual rooms using invisible or transparent fiber and miniature optical edge ONTs. This eliminates the bottleneck of Wi-Fi mesh backhaul: instead of relying on wireless links between mesh nodes (which lose 30–50% throughput per hop), FTTR provides a dedicated gigabit-plus optical path to every room. China Telecom has deployed over 10 million FTTR households. The technology is expected to spread globally as multi-gigabit WAN connections make Wi-Fi-only in-home distribution the new bottleneck. FTTR is driving demand for bend-insensitive G.657.A2 fiber, field-mountable connectors, and adhesive cable routing systems.
How does FTTH compare to 5G Fixed Wireless Access (FWA)?
FTTH and 5G FWA serve complementary, not competing, roles. FTTH provides dedicated, uncontended fiber capacity with a 30–50-year plant life and a clear upgrade path. 5G FWA provides rapid deployment over existing cellular infrastructure and is ideal for rural/low-density areas where fiber trenching costs are prohibitive. The key limitation of FWA is shared spectrum: per-subscriber throughput degrades with cell loading, whereas FTTH delivers consistent performance regardless of neighbor usage. The consensus deployment model is FTTH for 90–95% of addresses in a service area, FWA for the remaining 5–10% that are uneconomical for fiber.
What is the service life of an FTTH network?
The passive optical infrastructure (fiber, splitters, ODF panels) has a design life of 30–50 years. This is one of FTTH's most underappreciated economic advantages: the physical fiber plant is effectively a one-time investment. Active equipment (OLT line cards, ONTs) has a typical life of 7–10 years and can be upgraded independently of the fiber plant—for example, replacing GPON optics with XGS-PON optics on the same fiber. This decoupling of the long-life passive plant from the shorter-life active electronics is the architectural principle that makes FTTH the lowest-TCO broadband technology over a 30-year horizon.
How is China's FTTH market different from the rest of the world?
China's FTTH market is unique in three ways: (1) Scale—500M+ subscribers, more than the next 10 countries combined. (2) State-driven deployment—the "Broadband China" and "Dual Gigabit" strategies provide policy mandates and subsidies that compress deployment timelines. (3) Full vertical integration—China controls the entire supply chain from preform manufacturing (YOFC, Hengtong, FiberHome) to cable assembly to operator deployment, enabling cost structures ($150–300 per home passed) that are unachievable in fragmented Western markets. China is now transitioning from coverage (85%+ penetration) to quality upgrade (10G PON + FTTR), making it the world's largest market for next-generation PON equipment and indoor fiber components.
What role do optical splitters play in FTTH and how are split ratios determined?
Optical splitters are the heart of the passive distribution network. A 1:N splitter divides the downstream optical signal from one feeder fiber into N distribution fibers, each serving one subscriber. The split ratio determines the optical power budget: each 1:2 split costs ~3 dB, so a 1:64 split imposes ~18–20 dB loss. Standard GPON supports up to 1:64 (1:128 extended), XGS-PON supports 1:128 (1:256 extended), and 50G PON supports 1:256. The optimal split ratio is a trade-off: higher splits reduce feeder fiber count (lower trenching cost) but increase optical loss and reduce per-subscriber bandwidth. For typical suburban FTTH, 1:32 splitter or 1:64 splitter is standard; for dense urban, 1:64 or 1:128.PLC (Planar Lightwave Circuit) splitters are universally used for uniformity and reliability over fused-fiber alternatives.
References & Data Sources
[1] FTTH Deployment Status and Market Research Report. https://www.opelink.com/article/ftth-deployment-status-and-market-research-report-i01417i1.html
[2] Pmarketresearch. (2025). Air-Blown Micro-Fiber Cable Market: Global Size, Growth & Forecast to 2032.
[3] Hengtong Optic-Electric. (2025). Why Choose Air Blown Micro Cable? — Technical & Economic Analysis.
[4] Oufu Cable. (2025). EPFU Air Blown Micro Cable: Shenyang 5G & Utility Deployment Case Study.
[5] Hexatronic. (2025). How to Reduce Total Cost of Ownership (TCO) for Your Fiber Network.
[6] ITU-T. (2021). G.9804.3: 50-Gigabit-capable Passive Optical Networks (50G-PON): Physical Media Dependent (PMD) Layer Specification.
[7] ITU-T. (2016). G.984.x Series: Gigabit-capable Passive Optical Networks (GPON).
[8] ITU-T. (2010/2016). G.987 / G.9807 Series: 10-Gigabit-capable Passive Optical Networks (XG-PON / XGS-PON).
[9] IEEE. (2004). 802.3ah: Ethernet in the First Mile — EPON Standard.
[10] European Commission. (2023). Connectivity: Digital Decade Targets 2030 — FTTH/B Coverage Plan.
[11] NTIA (US). (2023). Broadband Equity, Access, and Deployment (BEAD) Program Overview.
[12] China Ministry of Industry and Information Technology. (2024). Broadband China & Dual Gigabit Strategy Status Report.
[13] ITU-T. (2016). G.657: Characteristics of a Bending-Loss Insensitive Single-Mode Optical Fibre and Cable.
[14] ITU-T. (2024). G.654.E: Characteristics of a Cut-off Shifted Single-Mode Optical Fibre and Cable for Long-Haul.
[15] CableLabs. (2023). DOCSIS 4.0 Technology Overview — Full Duplex DOCSIS & Extended Spectrum.
Related Guides
 Outdoor Fiber Optic Cable Installation Guide: Aerial, Duct & Direct Burial Methods
 Outdoor Fiber Optic Cable Types: GYTS, ADSS and OPGW Guide
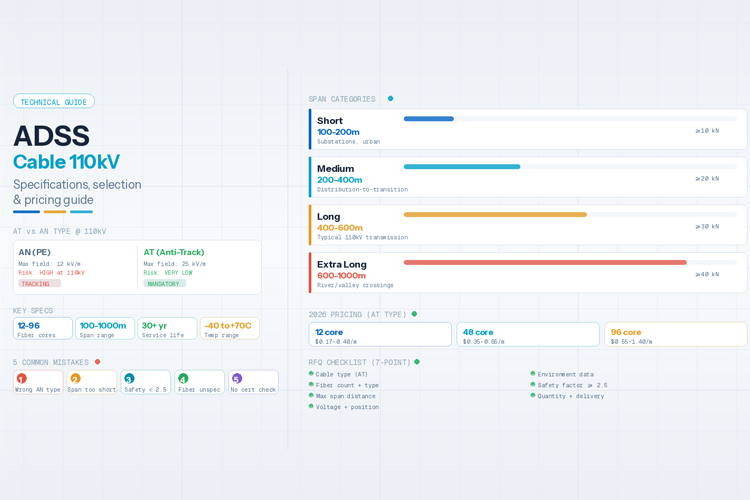 ADSS Cable for 110kV Power Line: Specifications, Selection & Pricing Guide
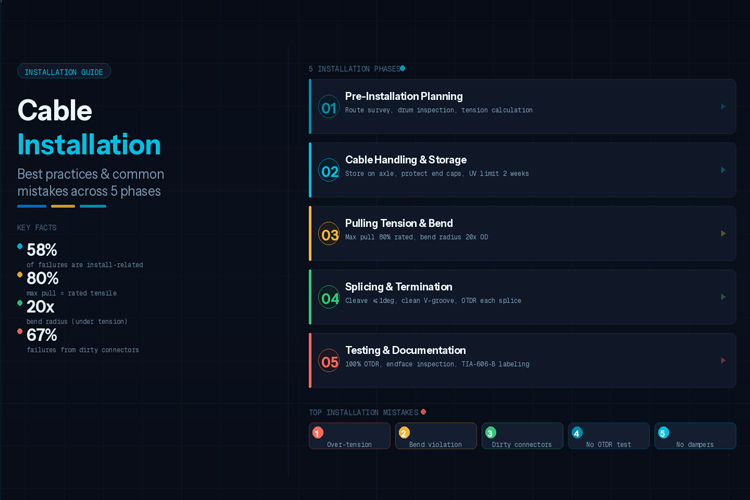 Fiber Cable Installation Best Practices & Common Mistakes


